Market Overview: Defining the Retail And Wholesale Market landscape
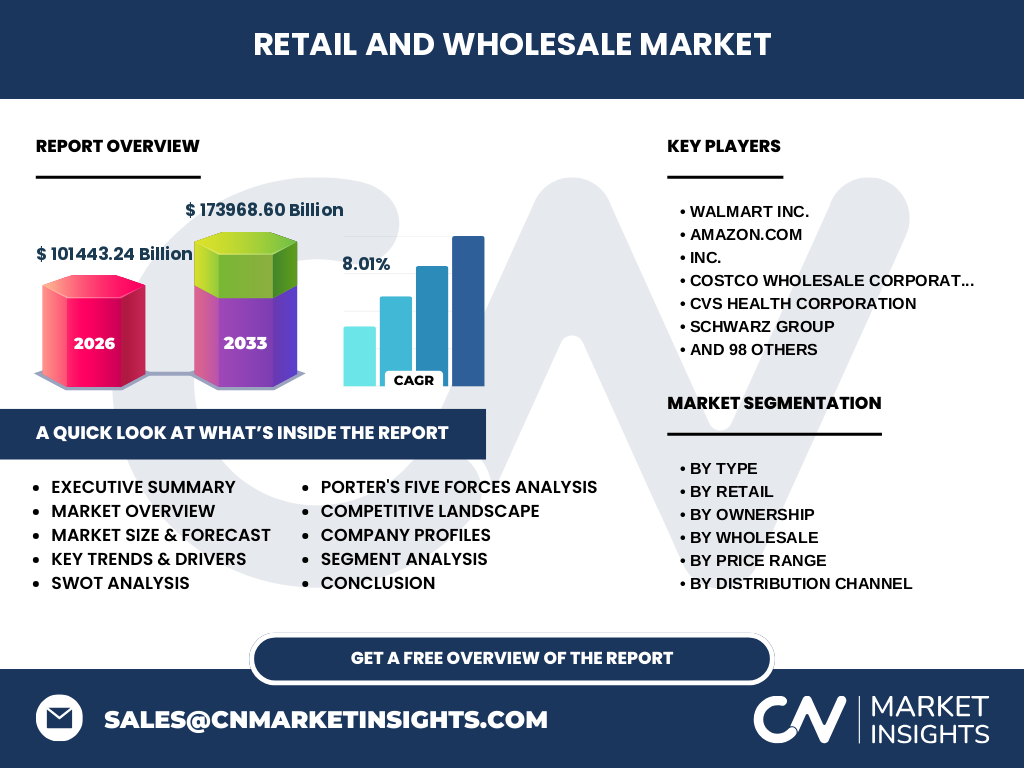
The Retail And Wholesale Market represents the critical bridge between raw commodity producers and end-consumers. Spanning global supply chains, this sector encompasses physical storefronts and complex distribution networks. With a valuation reaching 101,443.24 Billion in 2026, the industry serves as the primary engine for global consumption, integrating logistics, warehousing, and digital point-of-sale systems to manage the flow of goods from manufacturers to the final retail shelf.
What are the structural growth drivers, restraints, and strategic opportunities?
Growth is primarily fueled by digital transformation and shifting urbanization patterns. While logistical bottlenecks at major ports and fluctuating raw material costs present persistent restraints, the market sees massive opportunity in omni-channel integration. Companies like Walmart and Amazon are effectively bypassing traditional hurdles by utilizing AI-driven supply chain management, turning regional distribution challenges into distinct competitive advantages through high-speed last-mile delivery protocols.
Emerging trends and long-term growth patterns in the sector
The shift toward hyper-localized distribution is reshaping the sector. We are observing a departure from legacy centralized warehousing toward micro-fulfillment centers. Innovations from Jumbotail and ShopKirana highlight the trend of digitizing B2B interactions, allowing for faster inventory turns. These patterns indicate that agility, rather than mere scale, has become the primary determinant for sustained long-term expansion through 2033.
Post-pandemic trajectory: How did COVID-19 redefine the Retail And Wholesale Market?
The pandemic acted as an accelerant for digital adoption, forcing a permanent pivot toward contactless commerce. Retailers like Tesco and Carrefour SA had to rapidly pivot their e-commerce capabilities to survive, leading to a resilient recovery trajectory. Today, the focus has shifted from pandemic-era survival to optimizing hybrid retail models that prioritize consumer safety and supply chain transparency as core operational pillars.
Competitive Benchmarking: Strategic dynamics among industry leaders
The competitive landscape is highly concentrated, defined by aggressive vertical integration. Players like Costco Wholesale Corporation and Metro AG dominate through sheer bulk purchasing power, while regional giants like Lulu Group and Shoprite maintain localized dominance. Strategy revolves around private-label development and exclusive distributor partnerships, creating high barriers to entry for smaller, independent retail chains lacking deep capital access.
Executive Summary: Synthesis of current market findings
Our analysis confirms the Retail And Wholesale Market is positioned for robust expansion, with the market size projected to reach 173,968.60 Billion by 2033. A CAGR of 8.01% underscores the industry's underlying strength. Strategic success now depends on balancing physical infrastructure with data-centric retail solutions, ensuring that firms can capture value across diverse global economic environments through 2033.
Market Forecast: Projecting growth from 2027 to 2033
We project the market will sustain an upward trajectory, growing from its 2026 base to a massive 173,968.60 Billion by 2033. This 8.01% CAGR is underpinned by rising disposable incomes in emerging economies and the continued refinement of wholesale digital platforms. Investment capital is expected to flow toward automated inventory management systems that mitigate the margin-eroding effects of volatile inflationary pressures.
Segmentation Analysis: Breaking down the market ecosystem
The market is bifurcated into Retail and Wholesale, each serving distinct roles. Retail categories range from supermarkets and specialty stores to online platforms, focusing on end-user experience. Wholesale segments include merchant wholesalers, distributors, and manufacturer’s representatives. This ecosystem relies on Ownership structures—either independent retailers or large chains—to dictate the flow and pricing strategies within the global trade hierarchy.
Regional Performance: Geographic distribution of market value
Regional performance shows significant variance based on logistics infrastructure. While North America and Europe remain mature, high-value markets, Asia-Pacific is witnessing the most explosive growth. Regions utilizing advanced ports and seamless trade corridors demonstrate superior performance, as they reduce the time-to-market for consumer goods. Regional players like Seven & i Holdings exemplify how localized strategies succeed against global firms in high-density markets.
In-depth Regional Review: Detailed examination of key hubs
In the Middle East, firms like Majid Al Futtaim capitalize on premium retail demand, while in Eastern Europe, retailers like X5 Retail Group and Magnit dominate by optimizing discount distribution networks. These regions prioritize different price ranges, with economy segments driving volume in emerging markets, while premium ranges remain the focus for luxury-oriented retail chains operating in global hubs.
Company Profiles: Strategic positioning of industry leaders
Industry titans maintain their edge through differentiated market positioning. Amazon leads in digital-first wholesale, while CVS Health focuses on the niche intersection of retail and pharmaceutical supply chains. Meanwhile, Costco relies on a membership-led wholesale model that ensures recurring revenue. Each company maps their specific operational strengths to maximize their market penetration within their respective high-growth geographical sectors.
Porter's Five Forces: Assessing competitive intensity
Our analysis reveals high competitive intensity due to the proliferation of e-commerce marketplaces. The bargaining power of buyers is significant, facilitated by easy price comparison. Conversely, supplier power is moderated by the existence of powerful merchant wholesalers like Sysco. Entry barriers remain high, requiring immense capital expenditure in supply chain logistics and technology infrastructure to challenge established market participants.
SWOT Analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths: Established global supply chains and massive consumer reach. Weaknesses: High susceptibility to operational overhead and margin compression. Opportunities: Omni-channel expansion and AI-based inventory forecasting. Threats: Stringent regulatory bodies and disruptive geopolitical instability impacting cross-border trade. Success hinges on a firm's ability to navigate these threats while leveraging their technological strengths to capture emerging retail demand.
Value Chain Analysis: From raw materials to the end-user
The value chain starts with raw material procurement and moves through wholesalers and manufacturer’s representatives. Logistics providers and port authorities ensure the efficient movement of goods. Finally, retail channels—from hypermarkets to online retailers—deliver goods to the end-user. Efficiency is gained at each stage by minimizing middleman friction and maximizing data visibility, allowing for optimized replenishment cycles across the entire distribution network.
Investment Insights: Strategic recommendations and high-potential areas
Investors should target automation-ready infrastructure. High-potential areas include last-mile delivery innovation and B2B wholesale platforms. Companies like Alibaba or Ozon demonstrate that digitizing the wholesale flow is a high-yield investment. Firms that invest in resilient supply chains capable of bypassing traditional bottlenecks are likely to outperform the broader market as it moves toward the 2033 projection.
Conclusion: Key takeaways for stakeholders
The Retail And Wholesale Market is entering a period of transformative growth. With a projected valuation of 173,968.60 Billion, the market rewards those who integrate digital agility with traditional retail strength. Key success factors include supply chain diversification, data-driven pricing, and a relentless focus on the consumer experience, ensuring long-term profitability amidst a CAGR of 8.01%.
Research Methodology: How are baseline estimates triangulated?
Our methodology utilizes multi-modal triangulation. We synthesize trade registry data, macroeconomic indicators, and primary stakeholder interviews with sector experts. By cross-referencing company filings from entities like Walmart and Tesco with proprietary regional economic forecasts, we derive accurate baseline estimates. This rigorous approach ensures our 2026 market size of 101,443.24 Billion is grounded in verifiable, actionable market intelligence.
Scope of the report: Parameters and analytical limitations
The scope covers global Retail and Wholesale activities, segmenting by type, ownership, price range, and distribution channels. While we provide comprehensive coverage, regional nuances and regulatory variations—such as differing labor laws or import restrictions—remain limitations. The analysis assumes stable trade policies and focuses on market-level performance rather than individual micro-market volatility, providing a high-level strategic overview for global decision-makers.
Recent Developments: Strategic moves and industry announcements
The market is currently witnessing rapid strategic partnerships and tech-enabled launches. Recent moves include Flipkart Wholesale expanding its digital footprint and retailers like Woolworths optimizing their cold-chain distribution. These announcements signal a competitive pivot toward operational excellence and increased online penetration, reflecting how major players are preparing for the projected market growth through 2033 by shedding legacy systems.